

Walmart MoneyCard®
by Green Dot
3.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.8
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
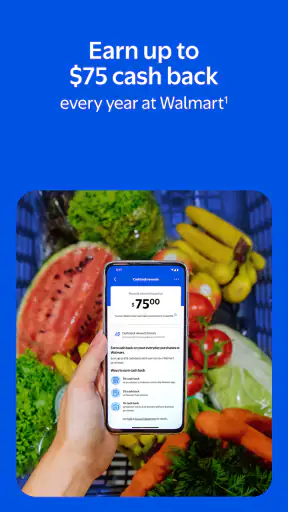
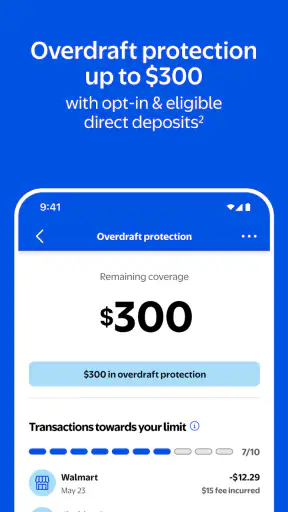
 Analysis by Getfullapps
I spent time with Walmart MoneyCard® as a finance app, and the main thing I noticed is that its value depends less on flashy tools and more on how easily it can fit into a prepaid-card routine. Green Dot presents it as a way to bank better through a newer mobile experience, but I found the more useful question is simpler: does having the card’s money-management access on your phone make everyday spending easier for you?
For someone who already uses Walmart MoneyCard, the app can act as the practical control point between the physical card and the account behind it. That makes it especially relevant for people who prefer a prepaid approach instead of opening a traditional checking account. I would not describe it as a universal replacement for every banking app, though. Its usefulness is tied closely to the Walmart MoneyCard ecosystem, so the right choice depends on how you manage money and what you expect from a finance app.
What the mobile experience is really built around
The central capability is straightforward: the app brings your Walmart MoneyCard activity into a phone-based interface. In everyday use, that means you can check the account from the same device you carry while shopping, commuting, or paying bills. I found that convenience more important than the store summary makes it sound, because prepaid spending works best when you can keep an eye on the available balance before making a purchase.
That balance-awareness changes the way the card feels. With cash, I have to remember what is left in my wallet. With a conventional bank account, I may need to think about pending transactions, linked services, or a separate debit card. A Walmart MoneyCard user can instead make the phone the first place to check before spending. The app is most useful when quick account visibility helps you avoid guessing.
It is worth separating the app from the card itself. Installing the application does not automatically make it a full-service bank account for every financial need. The experience is designed around Walmart MoneyCard access, so a person looking for a broad financial dashboard, investing tools, or a complete replacement for a traditional bank should approach it with different expectations. I see it as a focused companion rather than an all-purpose money center.
The product comes from Green Dot and is listed in the finance category. It is free to install, carries a mature seventeen-and-over content rating, and requires Android nine or later. The current release is version 2.7.0, which matters if you are using an older phone and are deciding whether the app will fit your device. On the Android side, that minimum requirement is not especially demanding, but compatibility is still something I would check before planning to rely on it.
Why the capability matters for prepaid spending
Prepaid cards are easier to use when the available balance is clear. That sounds obvious, but it affects real decisions: whether a grocery purchase will fit, whether a subscription payment might consume more than expected, or whether there is enough room for a bill later in the week. The app gives the card a more immediate digital layer, reducing the need to treat the physical card as a black box.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also like the psychological difference. A prepaid balance creates a natural spending boundary, while a credit card can make the cost of a purchase feel distant. Seeing the account through the app encourages a more deliberate habit. It does not magically create a budget, but it can support one if I check the balance before spending and reserve money for known obligations.
That is the first non-obvious strength: the app can turn a prepaid card into a more visible spending system. The benefit is not a sophisticated planning feature; it is the small pause before a transaction. For users who tend to lose track of cash or mix spending money with bill money, that pause can be genuinely useful.
How I would use it during a normal week
Imagine getting paid and setting aside money for rent, utilities, groceries, and transport. Instead of carrying the entire plan in your head, you use the Walmart MoneyCard account for the spending portion and check the app before purchases. At the supermarket, I would look at the available balance before reaching the checkout. Later, before a recurring bill processes, I would check again rather than assume the account still has enough.
That workflow is simple, but it is also where the app makes the most sense. The phone becomes a checkpoint, not merely a place to open an account once and forget it. I would recommend turning the check into a habit at predictable moments: before shopping, after a large purchase, and before a scheduled payment. Those three checks can prevent the common mistake of treating the original balance as if nothing has changed.
A second useful insight is that the app works better when paired with a personal reserve rule. I would avoid spending right down to the displayed balance, especially if several transactions are still in motion or if a bill is due soon. Leaving a cushion is more practical than assuming every amount shown is freely available for discretionary spending.
This is also where expectations need to stay realistic. A mobile balance view does not replace reading payment terms, checking merchant charges, or understanding how your own transactions appear. I would still review activity regularly and keep important payment dates in a separate calendar. The app can make information easier to reach, but it cannot make financial planning automatic.
The everyday situation where it fits best
The strongest scenario, in my opinion, is a person who wants a controlled spending account without making a traditional bank account the center of daily life. Perhaps you receive money, allocate a portion for weekly expenses, and want to know what remains while you are away from home. In that situation, the app’s focused nature is an advantage rather than a weakness.
It can also suit someone who shares household responsibilities but wants a clear boundary around a particular pool of spending money. For example, one person might use the card for groceries and transport while keeping other funds separate. The app makes it easier to check that pool before a purchase, which is more useful than relying on memory or scattered receipts.
Another good fit is a user who is moving away from cash but does not want the open-ended feel of credit. The app does not remove the need for discipline, but the prepaid structure and mobile visibility work together. I found that combination easier to understand than a credit balance that can keep growing while payments are postponed.
There is a practical tip here that generic app descriptions rarely mention: decide in advance what the account is for. If you use the card for groceries only, the app’s balance becomes meaningful. If you use it for every type of purchase without categories or a reserve, the same balance can become difficult to interpret. The app is clearer when the money has a job.
Where the experience can feel limiting
The main trade-off is focus. If you want one application to bring together multiple bank accounts, investments, detailed financial goals, and broad budgeting tools, this is probably not the experience I would choose first. Walmart MoneyCard® is more specialized, and specialization means fewer reasons to open it if you do not use the associated card.
I would also be cautious about treating the app as a substitute for financial education. A visible balance can tell you what appears to be available, but it does not by itself explain whether a payment is pending, how a merchant handles a transaction, or what a particular account action means. I would read the relevant account information and contact support when a transaction looks unfamiliar rather than relying on assumptions.
The mature seventeen-and-over rating is another practical point for households. This is not an app I would present as a child-focused money tool. A parent or guardian considering it for a younger person should think about account responsibility, supervision, and whether a prepaid card is appropriate for that situation instead of assuming the mobile interface makes it suitable automatically.
There is also a habit-related weakness: convenience can encourage checking without understanding. I can imagine opening the app repeatedly but still failing to account for upcoming bills. The strongest results come from combining the app with a simple written plan. I would note expected payments, keep a reserve, and use the app to verify the situation rather than asking it to create the plan for me.
Compared with cash, the app offers better visibility and less dependence on physical receipts, but cash can be simpler for someone who wants a hard spending limit in hand. Compared with a standard bank app, it is likely to feel more purpose-built around prepaid use rather than a broad set of banking relationships. Compared with a budgeting app, it is closer to an account-access tool than a full planning workspace. Those differences are not automatically flaws; they tell you what kind of user will benefit.
Who gets the most from it
I think the best audience is an existing Walmart MoneyCard user who wants convenient mobile access and is willing to check the account regularly. The app can make day-to-day spending feel more deliberate, especially for people who want to separate spending money from other funds. It is also a sensible option for someone who prefers a prepaid structure and does not need an expansive financial dashboard.
People who should probably skip it are those who do not use Walmart MoneyCard, those who need advanced budgeting across several accounts, and anyone expecting a full traditional-bank replacement in one download. I would also look elsewhere if your main goal is investments, detailed household forecasting, or a unified view of unrelated financial products. A more comprehensive banking or budgeting service would be a better match for those jobs.
The app’s public reception is mixed but reasonably established: it holds a 3.8 average from around 3.7 thousand ratings, with roughly 1.9 thousand written reviews and over 500 thousand installs. I would read that as evidence that people are using it, not as a guarantee that every account experience will be smooth. Finance apps are particularly sensitive to account circumstances, transaction timing, and support needs, so an average rating should inform your expectations rather than make the decision for you.
Because it is free, the main cost is not the download itself but the time and attention required to use it responsibly. I would not install it merely because it is available; I would install it if I had a Walmart MoneyCard and wanted a regular way to check and manage that card from my phone. That distinction keeps the app’s role clear.
My practical verdict after using it
My honest view is that Walmart MoneyCard® succeeds when I treat it as a focused companion for prepaid spending. Its strongest effect is giving the account a visible, convenient place in my daily routine. Checking before a purchase, checking after a large transaction, and checking before a bill are small actions, but they can make a prepaid setup feel far more manageable.
I would not recommend it as a universal finance solution, and I would not expect the app alone to organize a complicated financial life. Its limits become obvious when you want broad account aggregation or advanced planning. But those limits are easier to accept when your goal is simply to keep Walmart MoneyCard spending accessible and easier to monitor.
Green Dot’s app is therefore a good fit for a specific kind of user: someone who values a clear spending boundary, wants mobile access, and prefers a straightforward routine over a crowded financial dashboard. If that describes you, the free app is worth considering. If you need a complete banking command center, I would choose a broader alternative and keep this kind of focused prepaid tool only if its particular workflow genuinely helps you.
Pros
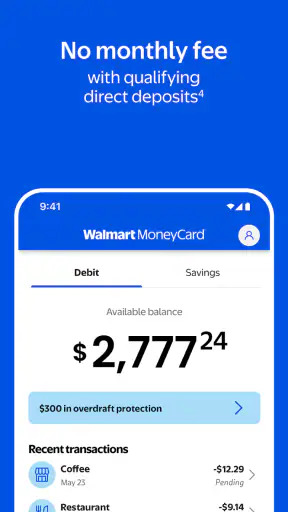
- No monthly fee when you receive qualifying direct deposits.
- Mobile check deposit lets you add funds without visiting a store.
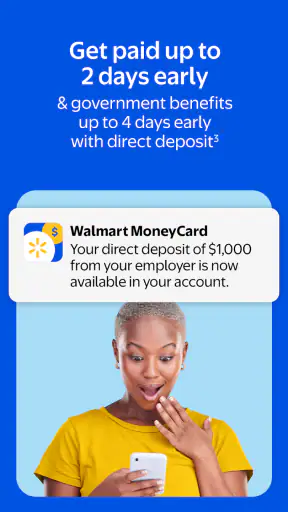
- Early direct deposit may provide access to eligible paychecks sooner.
- Card controls help you lock the card and manage transaction alerts.
- No overdraft fees because spending is limited to your available balance.
Cons
- Cash reload fees may apply at participating retail locations.
- Some features and fees vary by state or account eligibility.
- The card is not a traditional bank account with full banking services.
- ATM withdrawals can incur fees outside the MoneyCard network.
- Customer support experiences may vary, especially for account disputes.
FAQs for Walmart MoneyCard®
What is Walmart MoneyCard® and how does it work?
Walmart MoneyCard® is a reloadable prepaid debit card and mobile account designed for everyday spending, bill payments, direct deposit, and money management. It is not a traditional bank account, and you generally spend only the funds available on the card. After signing up and completing any required identity verification, you can manage your balance, transactions, deposits, and card settings through the app or website.
Are there fees for using Walmart MoneyCard®?
Walmart MoneyCard® may include fees depending on how you use the service. Possible charges can involve monthly maintenance, cash reloads, ATM withdrawals, expedited services, or other optional transactions. Fee amounts and waiver conditions may change, so it is important to review the current fee schedule before registering. The app usually provides useful account information, but the official terms should be treated as the final source.
Can I deposit money, receive direct deposit, or cash a check with Walmart MoneyCard®?
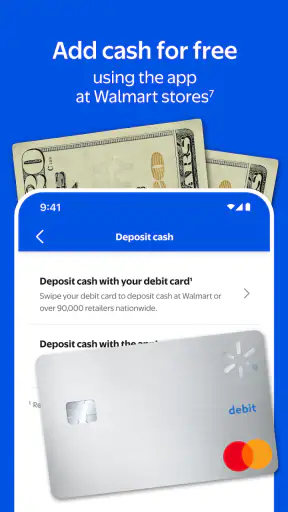
The card supports several ways to add money, although availability can depend on your account, location, and eligibility. You may be able to receive qualifying payroll or government direct deposits, add cash at participating retailers, transfer funds, or use supported mobile check-deposit features. Processing times and fees vary, so check the app carefully before choosing a deposit method.
Can Walmart MoneyCard® be used for online purchases, bills, and ATM withdrawals?
Yes, Walmart MoneyCard® can generally be used anywhere the applicable card network is accepted, including many online stores, physical retailers, and recurring bill services. ATM access may also be available, but withdrawal limits, operator surcharges, and account fees can apply. Before relying on the card for an important payment, confirm that your balance, card status, and merchant acceptance are all current.
Is Walmart MoneyCard® safe, and what should I do if my card or phone is lost?
The service includes security features such as account authentication, transaction monitoring, card controls, and options to lock or replace a card. Even so, users should protect their password, avoid sharing verification codes, and review transactions regularly. If your card or phone is lost, use the app or official customer-support channels to lock access promptly and report suspicious activity.

Walmart MoneyCard®
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via customeronlinefeedback@greendot.com, visit https://walmartmoneycard.com, or review their https://www.walmartmoneycard.com/agreements/privacy-policy.










